Purchase loans
Buy your next home with a plan
Know your budget before you shop, make stronger offers, and close on time, with Stephen guiding the loan from start to finish.
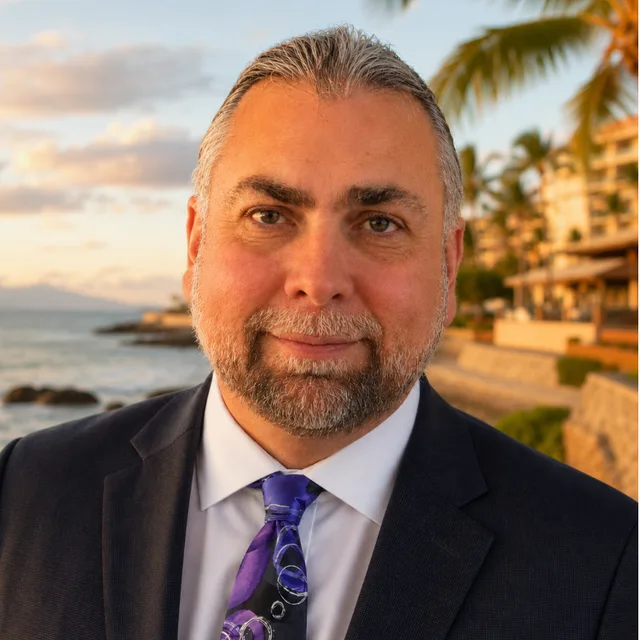
Stephen Patterson
Loan Officer · NMLS #1683302
Why pre-approval first
Shop with confidence
A pre-approval tells you what you can comfortably afford, and tells sellers you’re ready to close.
Stephen has spent more than 20 years on the real estate side as a broker-owner, so he knows what listing agents look for in an offer and how loan deadlines line up with contract deadlines. That helps you avoid surprises between “accepted” and “closed.”
What you’ll usually need
- Photo ID
- Recent pay stubs and W-2s, or tax returns if you’re self-employed
- Recent bank and asset statements
- Information on any other properties you own
- Permission to check your credit
Every loan is different. Stephen will send you a list made for your situation.
Step by step
From first call to closing
- 01
Have a quick conversation
Tell Stephen what you want to buy, where, and when. He’ll ask about your income, savings and credit so he can point you to programs that fit.
- 02
Get pre-approved
Stephen reviews your documents and credit, then issues a pre-approval letter. Now you know your budget and sellers know you’re serious.
- 03
Shop and make an offer
Work with the real estate agent of your choice. Stephen can update your pre-approval letter for each offer so it matches the home.
- 04
Lock, process and underwrite
Once you’re under contract, Stephen helps you decide when to lock your rate, orders the appraisal and keeps the file moving through underwriting.
- 05
Close and get your keys
You review your Closing Disclosure ahead of time, sign with the title company, and the home is yours.
Popular purchase programs
Loans buyers ask about most
Conventional
A standard loan that isn’t government-insured. Often a good fit when credit and savings are strong.
FHA
Insured by the Federal Housing Administration and designed to open the door for more buyers.
VA
For eligible veterans, service members and some surviving spouses.
USDA
For eligible homes in qualifying rural and suburban areas.
Down payment assistance
Programs that may help with up-front costs if you qualify. See the first-time buyer guide.
Bank statement & non-QM
For self-employed buyers and income that doesn’t fit a standard box.
Questions
Buying FAQ
How long does a pre-approval take?
Often it can be done quickly once Stephen has your documents. Complicated income or credit can take longer. He’ll tell you up front what to expect.
Does a pre-approval hurt my credit?
A pre-approval usually includes a credit check, which can have a small effect on your score. Several mortgage credit checks within a short shopping window are generally treated as one inquiry by the scoring models.
Do I need a real estate agent?
It’s up to you. You are always free to choose your own lender and real estate agent. If you’d like a referral, Stephen can point you to agents he trusts.
Can I buy if I’m self-employed?
Yes, often. Besides tax-return loans, NEXA offers bank statement and other flexible-documentation programs. Stephen will compare them for you.
Get started
Tell Stephen about your plans
He’ll follow up with your options and next steps. Looking for homes? Search withASAP Realty Group, Powered by AXEN Realty (opens in a new tab).
Ready when you are
Call or text Stephen, book a quick call, or start your application online.
Stephen Patterson · Loan Officer · NMLS #1683302